


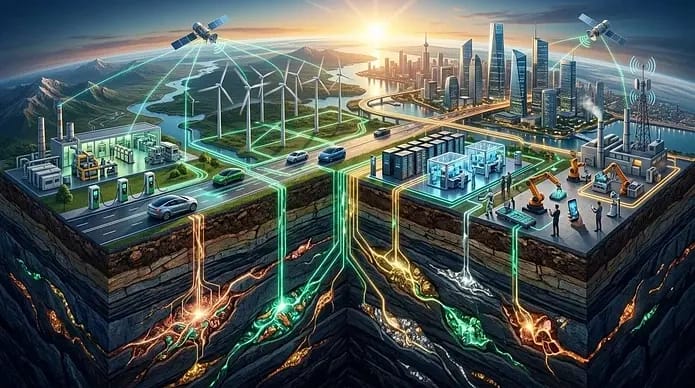
Rare Earth Minerals: Uses and Supply Chain Risks
Rare earth minerals rarely appear in headlines beside artificial intelligence, electric vehicles or renewable energy. Yet many of the technologies reshaping the world economy would struggle to function without them.
These materials help produce powerful magnets, efficient electric motors, smartphone displays, data-storage systems, medical equipment, aerospace components and advanced defense technologies. A small amount of the right rare earth element can give a product properties that are difficult—or expensive—to reproduce with another material.
That makes rare earth minerals economically important far beyond the relatively modest size of their market.
The central issue in 2026 is not that the planet is about to run out of rare earths. According to the U.S. Geological Survey’s rare-earth overview, these elements are relatively abundant in Earth’s crust.
The real problem is more complicated: commercially useful deposits are harder to develop, separating individual elements is technically demanding, and the processing and manufacturing stages are concentrated in a small number of countries.
That combination has turned rare earth minerals into a hidden pressure point for the global economy.
Quick take
- Rare earth minerals include 17 metallic elements with valuable magnetic, optical and chemical properties.
- They are not always geologically rare, but economical deposits and processing capacity are limited.
- Neodymium, praseodymium, dysprosium and terbium are particularly important for high-performance permanent magnets.
- China remains the dominant participant in rare earth refining and magnet manufacturing.
- Mining more material will not solve the problem unless countries also develop separation, refining and component-production capacity.
- Recycling, alternative motor designs and more efficient material use can reduce—but not eliminate—supply risks.
- Rare earth disruptions can affect industries worth far more than the minerals themselves.
What are rare earth minerals?
The term “rare earth minerals” generally refers to mineral resources containing one or more of 17 rare earth elements. These consist of the 15 lanthanides on the periodic table, together with scandium and yttrium.
The group includes:
- Lanthanum
- Cerium
- Praseodymium
- Neodymium
- Promethium
- Samarium
- Europium
- Gadolinium
- Terbium
- Dysprosium
- Holmium
- Erbium
- Thulium
- Ytterbium
- Lutetium
- Scandium
- Yttrium
Despite their name, many rare earth elements are not exceptionally scarce.
Cerium, for example, is more abundant in Earth’s crust than several familiar metals. The word “rare” reflects the historical difficulty of identifying, separating and producing these elements in pure, usable forms.
Rare earths commonly occur mixed together inside ores rather than in concentrated deposits of a single element. Because they have similar chemical properties, separating them requires multiple processing stages, specialized knowledge and carefully controlled chemical systems.
This is the first essential lesson: possessing rare earth deposits is not the same as possessing a complete rare earth industry.
Why rare earth minerals are difficult to replace
Rare earth elements are valuable because their atomic structures produce unusual magnetic, optical, catalytic and heat-resistant characteristics.
Manufacturers use them to make products:
- Smaller without sacrificing performance
- Lighter while retaining strength
- More energy-efficient
- Resistant to extreme temperatures
- Capable of producing powerful magnetic fields
- Able to display precise colors
- More effective at controlling chemical reactions
A manufacturer can sometimes replace a rare earth material with another substance. But the substitute may increase weight, reduce efficiency, require a redesigned product or perform poorly under demanding conditions.
That is why substitution is not simply a question of finding another metal. Engineers must consider the performance, cost, reliability and manufacturing implications of changing an entire system.
Seven powerful uses of rare earth minerals
1. Electric vehicles and industrial motors
Some of the most important rare earth applications are found in permanent magnets.
Neodymium-iron-boron magnets can produce an extremely strong magnetic field relative to their size and weight. Praseodymium may be included to improve performance, while dysprosium and terbium can help magnets retain their properties at higher temperatures.
These characteristics make rare earth magnets valuable in compact, efficient electric motors.
Electric vehicles are not the only source of demand. Similar motors appear in factory equipment, robotics, elevators, pumps, air-conditioning systems and countless automated machines.
Not every EV motor requires rare earth magnets. Induction motors and other designs can operate without them. However, changing motor technology may introduce trade-offs involving efficiency, weight, cost or manufacturing complexity.
As electric transportation expands alongside the broader global energy transition, access to reliable magnet supplies will become increasingly important.
2. Wind turbines and electricity generation
Permanent-magnet generators are used in certain wind turbines, particularly large direct-drive systems.
These designs can reduce the number of moving parts and eliminate the need for a conventional gearbox. That can be valuable for offshore turbines, where maintenance is difficult and expensive.
Not all wind turbines contain rare earth magnets, so renewable-energy growth does not translate directly into identical rare earth demand across every project. Nevertheless, the scale of planned wind development makes high-performance magnet availability an important industrial consideration.
Rare earths are also present in other energy technologies, including specialized batteries, sensors, lighting systems and equipment used to control electricity networks.
The connection between clean energy and rare earths demonstrates an uncomfortable reality: building a lower-carbon economy still requires substantial mining, chemical processing and industrial infrastructure.
3. Smartphones and consumer electronics
Rare earth minerals help make modern electronics compact, colorful and responsive.
They can be found in smartphone speakers, vibration units, microphones, screens, camera systems and electronic components. Europium and terbium contribute to display colors, while neodymium magnets enable powerful sound and mechanical performance in very small spaces.
Individual devices may contain only tiny quantities. Multiplied across hundreds of millions of phones, computers, headphones and household electronics, however, those quantities become economically significant.
This also creates a recycling challenge. Recovering a small amount of material from a complicated product can cost more than the recovered mineral is worth—especially when devices were not designed for easy disassembly.
4. Artificial intelligence and data centers
Rare earth minerals do not perform AI calculations in the way advanced processors do. Their role is less visible but still important.
Data centers contain servers, storage devices, electric motors, cooling equipment, power systems and communication technologies. Rare earth elements may appear in hard-disk drives, high-efficiency motors, sensors, capacitors and other specialized components supporting that infrastructure.
The connection becomes stronger as AI expands into robotics, autonomous equipment and physical machines. These systems combine computing power with motors, actuators, cameras and precision sensors.
That means the competition described in the global AI leadership race is not only about algorithms and semiconductor fabrication. It also depends on reliable access to energy, equipment and specialized materials.
Investors following fluctuations in AI chip stocks should therefore remember that the technology economy rests on a much broader physical supply chain.
5. Aerospace and defense systems
Rare earth elements are used in aircraft, guidance technologies, radar, communications equipment, sensors, satellites, precision motors and high-temperature alloys.
Samarium-cobalt magnets are especially valuable in certain demanding applications because they can maintain magnetic performance at elevated temperatures and resist corrosion.
Defense supply chains place an unusually high value on reliability. A material that represents a tiny portion of a system’s total cost can still prevent that system from being manufactured if no qualified substitute is available.
For this reason, governments increasingly treat rare earth processing as an economic-security and national-security capability rather than an ordinary commodity business.
6. Healthcare and medical technology
Rare earths support several important healthcare applications.
Gadolinium compounds are used as contrast agents in some magnetic resonance imaging procedures. Other rare earth elements are found in medical lasers, imaging equipment, diagnostic systems and specialized electronic components.
These applications illustrate why rare earth supply security affects more than headline industries such as electric vehicles or defense. Interruptions can reach hospitals, laboratories, telecommunications providers and manufacturers of precision instruments.
They also show why sweeping restrictions require careful design. Governments attempting to protect supply chains must consider civilian and scientific uses alongside strategic applications.
7. Catalysts, glass and advanced manufacturing
Cerium and lanthanum have long-standing industrial uses that receive less public attention.
Cerium oxide is used in glass polishing and catalytic applications. Lanthanum contributes to camera lenses, catalysts and certain battery chemistries. Yttrium, europium and terbium help produce specialized lighting, displays and ceramics.
Rare earths can improve the durability, clarity, efficiency or heat resistance of industrial products even when used in small quantities.
This helps explain their economic importance. Rare earth markets are much smaller than markets for oil, steel or copper, but they support high-value manufacturing chains that cannot always tolerate an interruption.
The real bottleneck is processing—not geology
Public discussions often focus on where rare earths are mined. Mining, however, is only the beginning of the supply chain.
A simplified mine-to-magnet process includes:
- Finding and evaluating a suitable deposit.
- Developing and permitting the mine.
- Extracting and concentrating the ore.
- Cracking or leaching the mineral concentrate.
- Separating closely related rare earth elements.
- Refining individual oxides.
- Converting oxides into metals and alloys.
- Manufacturing high-performance magnets.
- Integrating magnets into motors and other products.
Each stage requires capital, technical knowledge, environmental controls, customers and infrastructure.
The International Energy Agency’s rare earth analysis found that China accounted for approximately 60% of mined magnet rare earth production in 2024 and 91% of refined output. Its position in permanent-magnet manufacturing was even stronger.
There has since been some diversification. The IEA reported in July 2026 that projects in the United States and increased production in Malaysia reduced the leading supplier’s refining share from more than 90% in 2023 to approximately 85% in 2025.
That is progress, but it still represents an exceptionally concentrated supply chain.
Building a mine without developing separation and magnet capacity can leave the most strategically valuable processing stages under the control of existing suppliers. This is why the restructuring of global trade and supply chains has become so important for manufacturers.
Why concentration creates an alarming economic risk
Rare earths present a classic mismatch between input value and downstream importance.
The minerals contained in a vehicle may represent a very small share of its total price. Yet the vehicle cannot be completed without the required component.
According to the IEA’s 2026 Critical Minerals Outlook, rare earths represent around 40% of a permanent magnet’s cost but less than 1% of a vehicle’s value. The agency estimated that even tripling rare earth prices would increase a car’s cost by only about 0.1%.
A total supply interruption is much more damaging than a manageable increase in cost.
Export controls introduced in 2025 demonstrated that concentration was not merely a theoretical concern. Some automakers reportedly reduced capacity utilization or temporarily halted operations while companies sought licenses and alternative supplies.
The IEA estimated that full implementation of expanded controls could place approximately $6.5 trillion in annual downstream production outside China at risk across automotive, technology, defense and energy industries.
Readers interested in the wider competition involving lithium, cobalt, graphite, copper and other strategic materials can explore The Light Span’s analysis of the critical minerals race in 2026. This article, by contrast, focuses specifically on how rare earth elements and their processing chains work.
Can the world diversify rare earth supplies?
Yes—but diversification will take more than opening new mines.
Australia, the United States and several other countries are expanding production or developing new projects. Malaysia has an established role in processing, while governments in Europe, Asia and North America are supporting domestic supply-chain initiatives.
Successful diversification requires four connected capabilities:
Responsible mining
New mines need realistic permitting systems, community engagement, environmental safeguards, infrastructure and customers willing to enter long-term purchase agreements.
Commercial-scale separation
Separating rare earth elements is technically difficult and can generate hazardous waste. New facilities need experienced workers, dependable feedstock and competitive operating costs.
Magnet manufacturing
A country may produce separated oxides and remain dependent on imported metals, alloys or finished magnets. Resilience requires investment further downstream.
Predictable demand
New suppliers often compete against experienced, lower-cost incumbents. Manufacturers may need to accept a modest “security premium” through long-term contracts that make alternative projects financially viable.
The objective should not be complete national self-sufficiency. That would be costly and unrealistic for many economies. A more practical goal is a network of trusted suppliers, multiple processing locations, strategic inventories and transparent trade relationships.
Can recycling solve the problem?
Recycling can become a meaningful part of the solution, but it cannot immediately replace primary mining.
Rare earths are difficult to recover because they are often dispersed in small quantities across complex products. Collection systems may be weak, product compositions may be unknown, and conventional separation can be chemically intensive.
A more promising approach is recovering whole magnets or magnet alloys from large, identifiable products such as electric motors, wind turbines and computer drives.
The U.S. Department of Energy’s rare earth recycling research emphasizes that improved separation chemistry could reduce both recovery costs and environmental effects. Newer projects are investigating mine waste, electronic waste and end-of-life magnets as alternative sources.
Recycling offers several advantages:
- It reduces pressure on new mines.
- It recovers value from existing products.
- It can shorten supply chains.
- It may use less energy than primary production.
- It reduces the amount of material sent to landfills.
- It provides supply in regions without major deposits.
Its contribution should grow as the first large generations of electric vehicles and modern wind turbines reach retirement. Even then, rapidly increasing demand means recycled supply will complement rather than eliminate mining.
What businesses and investors should watch
Rare earth markets can be difficult for ordinary investors to evaluate. They are relatively small, prices can be opaque, and government policies may strongly influence project economics.
A company announcing a large resource has not necessarily built a viable business.
Investors should examine:
- Which rare earth elements are actually present
- Whether the deposit contains valuable magnet materials
- Ore grades and expected recovery rates
- Separation and refining arrangements
- Environmental and permitting requirements
- Capital and operating costs
- Customer agreements
- Exposure to changing prices
- The timeline to commercial production
- Whether downstream magnet capacity exists
Businesses that consume rare earth components should look beyond their direct suppliers. A motor purchased from a domestic company may still contain magnets made from imported material processed in one concentrated region.
That makes multi-tier supplier mapping, alternative product qualification, careful inventory management and recycling agreements increasingly valuable.
What happens next?
The rare earth economy is moving toward gradual diversification rather than rapid independence from existing suppliers.
More mines and processing facilities will open outside China. Recycling will improve. Some manufacturers will redesign motors or reduce the amount of heavy rare earth material they use. Governments will expand strategic inventories and provide financial support for difficult midstream projects.
But the established supply chain has enormous advantages in scale, skills, infrastructure and manufacturing experience. Reproducing those capabilities will take years.
The most successful countries will be those that treat rare earths as an industrial ecosystem—not merely a mining opportunity.
They will connect geological resources with processing knowledge, responsible environmental management, skilled workers, component manufacturing and dependable customers.
Frequently asked questions
Are rare earth minerals actually rare?
Most are not exceptionally rare in Earth’s crust. The challenge is finding economically attractive concentrations and separating closely related elements into usable products.
Which rare earth elements are most important for magnets?
Neodymium and praseodymium are central to many powerful permanent magnets. Dysprosium and terbium can improve performance at high temperatures, although manufacturers continually work to reduce the amounts required.
Do all electric vehicles need rare earth minerals?
No. Some electric motors use designs that do not require rare earth permanent magnets. However, rare earth magnets remain attractive because they can provide excellent efficiency and power in a compact package.
Does China control all rare earth mining?
No. Rare earths are also mined in the United States, Australia and other countries. China’s greatest strategic advantage lies across the wider chain, particularly separation, refining and permanent-magnet manufacturing.
Can rare earth magnets be recycled?
Yes. Magnets can be recovered and processed through several methods, but collection, product disassembly, mixed compositions and economic viability remain challenges.
Will new mines eliminate supply risk?
Not by themselves. New mines must be connected to separation plants, metal and alloy production, magnet manufacturing and qualified customers.
Final thoughts
Rare earth minerals are a powerful example of how the modern economy depends on small, easily overlooked inputs.
They help smartphones produce sound, electric motors operate efficiently, wind turbines generate power, medical systems create images and defense equipment function in demanding conditions. Their value comes not from the amount used but from the performance they make possible.
The world has enough geological resources to develop a more diversified system. The harder task is building the processing facilities, technical expertise, environmental safeguards and downstream manufacturing capacity required to turn those resources into dependable products.
Rare earth minerals will therefore remain central to technology, energy and economic-security debates well beyond 2026.
Understanding them reveals a larger truth about the global economy: the most important material is not always the one used in the greatest quantity. Sometimes it is the tiny component without which everything else stops.
Continue reading more

