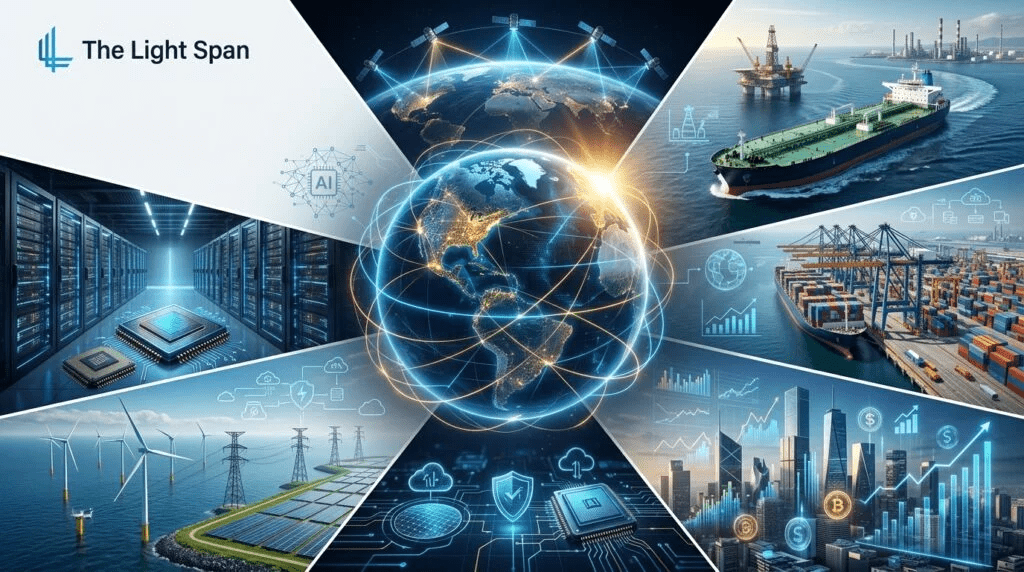
The week of July 13–19, 2026 brought several stories that appeared separate but shared one underlying theme: economic power was becoming inseparable from technology and energy capacity. AI investment pushed demand for chips, data centers and electricity, while geopolitical risk kept oil and shipping routes in focus. Markets had to evaluate both the promise of a technology boom and the cost of building it.
This weekly brief records what mattered during that specific period and explains why those developments still belong in the same story. It is a historical snapshot, not a live market update; prices and forecasts should be read in the context of July 13–19.
Every week brings hundreds of headlines.
Only a handful truly reshape the world.
This week’s developments highlighted three defining themes of 2026: the accelerating race for artificial intelligence leadership, renewed geopolitical tensions affecting energy markets, and the continued transformation of the global economy into a more fragmented—but strategically connected—system.
Here’s what mattered most this week.
🌍 Global Economy
Oil Markets Return to the Spotlight.
Oil prices recorded one of their strongest weekly performances in months as renewed tensions in the Middle East raised concerns about global energy supplies.
Although no major supply disruptions have occurred, markets reacted to the possibility that strategic shipping routes could face increased risks.
Higher crude prices immediately renewed concerns about inflation, transportation costs, and central bank policy.
Why it matters
Energy prices remain one of the fastest ways geopolitical events ripple through the global economy.
Global Markets Stay Cautious
Stock markets experienced another volatile week as investors balanced strong corporate investment in artificial intelligence with concerns over inflation and geopolitical uncertainty.
Technology stocks continued attracting capital, while sectors dependent on energy costs remained under pressure.
The trend to watch
Markets are increasingly reacting to geopolitics just as much as earnings reports.
🤖 Technology
AI Infrastructure Becomes the Next Mega Industry.
The AI conversation continues shifting away from chatbots toward infrastructure.
Around the world, governments and technology companies are investing billions into:
• Data centers
• Semiconductor manufacturing
• High-speed networking
• Electricity generation
• Cloud computing infrastructure
Rather than software alone, the future AI race will increasingly be determined by computing capacity.
Why it matters
The companies building AI infrastructure may ultimately become just as important as those building AI models.
China Expands Its Global AI Strategy
China used this week’s World Artificial Intelligence Conference to present a broader vision for international AI cooperation.
Rather than focusing only on technology, Beijing emphasized AI governance, open-source development, and partnerships with developing nations.
The move reflects China’s ambition to become a global leader in both AI innovation and international standards.
🌐 Geopolitics
Economic Competition Is Replacing Traditional Globalization
This week reinforced an increasingly clear trend.
Countries are reorganizing trade relationships around strategic partnerships rather than simply pursuing the lowest costs.
Supply chains continue diversifying.
Governments are investing in domestic semiconductor production.
Businesses are expanding manufacturing across multiple regions to improve resilience.
Globalization isn’t ending.
It’s evolving.
Energy Security Remains Central
Recent geopolitical developments reminded governments that energy security remains one of the foundations of economic stability.
Countries continue investing in renewable energy while also seeking more diversified oil and natural gas supplies.
The transition toward cleaner energy continues, but traditional energy resources remain strategically important.
📈 Markets to Watch Next Week
Investors will closely monitor:
• Developments in global oil markets.
• AI infrastructure investment announcements.
• Semiconductor industry updates.
• Central bank commentary on inflation.
• U.S.–China technology relations.
• Manufacturing and business activity data.
These stories are likely to influence both financial markets and broader economic sentiment in the coming days.
Why These Stories Mattered Together
The defining economic stories of the week were connected through physical constraints. AI looked like a software revolution, but its expansion depended on semiconductors, data centers and power plants. Oil looked like a traditional commodity story, but price moves affected inflation, interest-rate expectations and the cost of manufacturing new technology infrastructure. Geopolitical competition shaped both.
1. Oil risk returned through expectations
Oil markets react before an actual shortage appears. Traders price the possibility that conflict, sanctions or disruption to a strategic waterway could reduce future supply. That risk premium can rise quickly and disappear just as quickly, which is why a strong weekly move does not by itself prove a lasting energy crisis.
The forces behind higher oil prices in 2026 included geopolitics, supply discipline, inventories and demand expectations. For businesses, the lesson was to watch transport and production costs rather than treating crude as a financial-market statistic. For households, the effect could arrive through fuel, food delivery and airline prices.
2. AI infrastructure became the hidden center of the technology boom
The week reinforced that AI leadership required much more than a strong model. It required accelerators, high-bandwidth memory, networking equipment, cooling, fiber and dependable electricity. That is why the AI infrastructure race was beginning to resemble an industrial investment cycle.
The International Energy Agency later quantified the scale of the pressure: global data-center electricity consumption was on a path to roughly double by 2030. That connection between computing and power helps explain why utilities, grid equipment and energy policy were becoming relevant to technology investors.
3. China’s AI strategy moved into diplomacy
China was seeking influence not only by improving domestic technology but also by presenting AI cooperation as a development and governance offer. Open models, training, infrastructure and participation in international standards could help Beijing build relationships with governments that wanted access without complete dependence on American platforms.
The detailed analysis of China’s AI diplomacy strategy shows the opportunity and limitation. China’s manufacturing ecosystem and state coordination support a broad offer, while advanced-chip restrictions and data-governance concerns can limit trust. The contest was becoming one of ecosystems rather than a simple model benchmark.
4. Globalization was becoming selective
Companies were not abandoning global trade. They were identifying the products that could stop an entire operation if a border closed or an export rule changed. Semiconductors, critical minerals, energy and telecommunications received special attention because substitutes could not be created quickly.
This is the practical meaning of a global economy splitting into competing blocs. Ordinary commerce can continue even as strategic supply chains become more regional and politically screened. The resulting system is neither full globalization nor complete separation.
5. The chip rally faced a valuation test
AI-related stocks had benefited from expectations of sustained infrastructure spending. By this week, investors were increasingly asking how quickly that spending would generate revenue and whether valuations allowed any room for delay. A correction did not necessarily contradict long-term semiconductor demand; it changed the price investors were willing to pay for that demand.
The AI stock correction was therefore an early sign of a maturing market. Attention was shifting from whether AI would grow to which companies could convert growth into durable margins and cash flow.
A Reader’s Checklist From the Week
- Separate events from trends. A weekly oil move can reverse, while underinvestment in grids may persist for years.
- Follow bottlenecks. Chips, electricity, transformers and permits can matter more than headline model releases.
- Watch policy and markets together. Export controls, industrial subsidies and sanctions can change commercial outcomes.
- Distinguish industry growth from investment return. A fast-growing market can still contain overpriced assets.
- Look for second-order effects. AI demand can affect utilities and construction; oil risk can affect inflation and interest rates.
What the Week Revealed About 2026
The week showed that the digital economy had become deeply physical. Technology leadership depended on factories, mines, data centers, transmission networks and shipping routes. At the same time, those assets were becoming instruments of national strategy.
It also showed why investors and business leaders needed a wider lens. A company could have strong demand but face a power constraint. A country could have advanced models but lack international trust. A fall in inflation could be interrupted by energy risk. The most important stories were happening at the intersections.
That is the lasting value of this weekly brief: not a list of disconnected headlines, but a record of the moment when AI, energy and geopolitics became parts of the same economic system.
Questions the Following Weeks Needed to Answer
A useful weekly brief should leave readers with testable questions rather than confident predictions. The first was whether oil’s risk premium would be confirmed by disrupted supply. If shipping continued and inventories remained adequate, part of the move could reverse. If physical deliveries tightened, the effect would spread into inflation and central-bank expectations.
The second question was whether technology companies would maintain their infrastructure commitments. Announced spending can change when construction costs rise or expected demand is delayed. Investors needed to watch orders for servers, networking and electrical equipment alongside cloud revenue and customer use.
The third was whether governments would turn technology rivalry into lasting institutions. Export controls and subsidies matter, but standards bodies, research partnerships and financing programs create deeper influence. China’s diplomatic initiatives and American private-sector alliances were both attempts to shape those networks.
The fourth concerned the middle powers. Countries across Southeast Asia, the Gulf, Latin America and Africa had reasons to work with both Washington and Beijing. Their ability to attract data centers, manufacturing and energy investment could prevent the emerging system from becoming two completely closed blocs.
Finally, markets needed evidence that AI infrastructure would create broad productivity gains. Selling chips and constructing data centers could drive investment, but the larger economic promise depended on businesses using AI to reduce costs, improve services and create new products. Without that second stage, infrastructure spending risked outrunning returns.
How to Use a Historical Weekly Brief
This article should not be used for current prices or trading decisions. Its value is analytical: it captures what information was available during July 13–19 and which uncertainties were visible at the time. Readers reviewing later outcomes can compare them with those signals without rewriting history.
That comparison helps distinguish a good process from a lucky forecast. A useful analysis identifies drivers, alternative outcomes and evidence that would change the conclusion. It does not pretend uncertainty never existed. For The Light Span, the week remains important because it showed a durable pattern—the merging of technology investment, energy security and geopolitical strategy.
Another reason to preserve the brief is that weekly narratives influence decisions before the full evidence arrives. Companies may hedge energy costs, delay investment or accelerate supply-chain changes in response to perceived risk. Investors may rotate between sectors before earnings confirm the story. Those reactions can affect the economy even when the original fear later fades.
By placing the week’s oil, AI and geopolitical developments in one framework, readers can see how expectations travel across markets. A concern about a shipping route can influence fuel prices; fuel can influence inflation; inflation can influence interest rates; and rates can influence the financing of new data centers. The chain of effects is often more important than any isolated headline.
The week therefore offered a practical lesson in systems thinking: follow how one constraint changes decisions elsewhere. That approach remains useful long after the dates and market prices have moved on.
💡 The Light Span Perspective
This week’s events reinforce a broader shift taking place across the global economy.
Artificial intelligence is no longer simply a software revolution.
Energy is no longer only a commodity.
Supply chains are no longer designed solely around efficiency.
Technology, geopolitics, infrastructure, and economics are becoming increasingly interconnected.
Understanding how these forces interact—not just the individual headlines—will be essential for businesses, investors, and policymakers throughout the remainder of 2026.
Quote of the Week
“The future will belong not only to those who create breakthrough technologies, but also to those who build the infrastructure, alliances, and institutions that allow those technologies to shape the world.”
— The Light Span Weekly Brief
Coming Up Next Week
Here’s what we’ll be watching:
- 🤖 The next phase of the global AI infrastructure race.
- 🛢️ Oil prices and energy market volatility.
- 🌍 U.S.–China technology and trade developments.
- 📈 Global market reactions to inflation and interest rate expectations.
- ⚡ Renewable energy and semiconductor investment announcements.
Subscribe to our channel:
https://www.youtube.com/@TheLightSpan